Terms and conditions apply. Please refer to Product Summary(ies) for more information about these insurance plans.
Footnotes
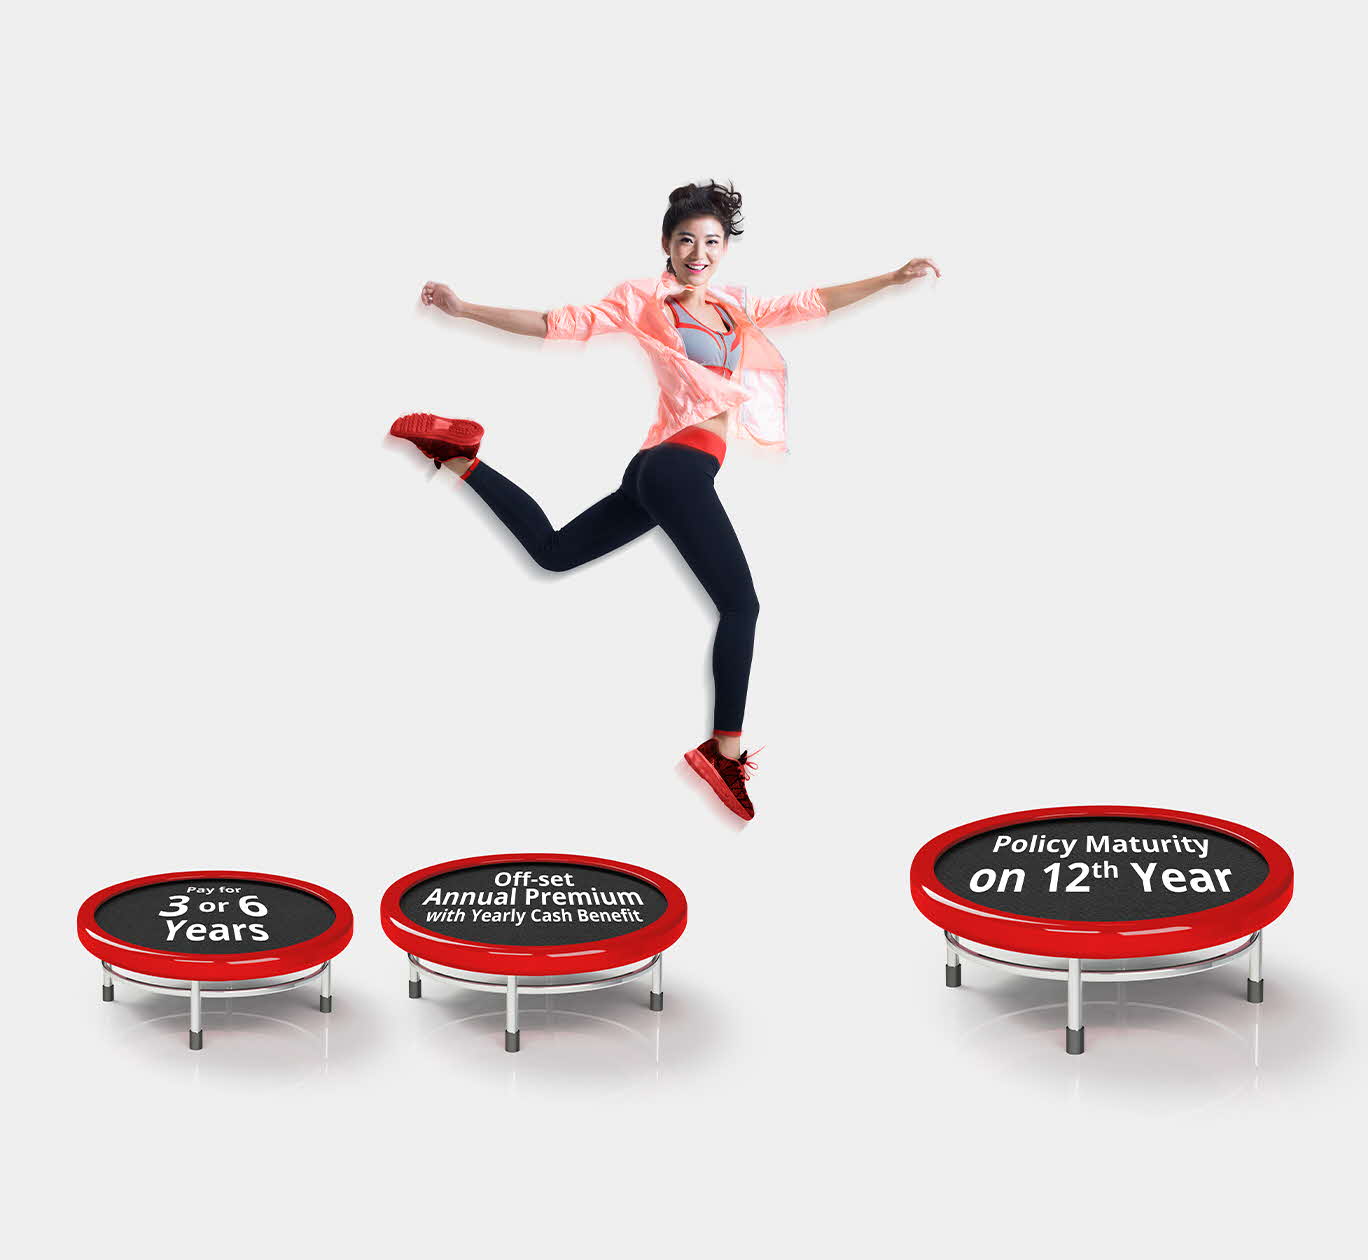
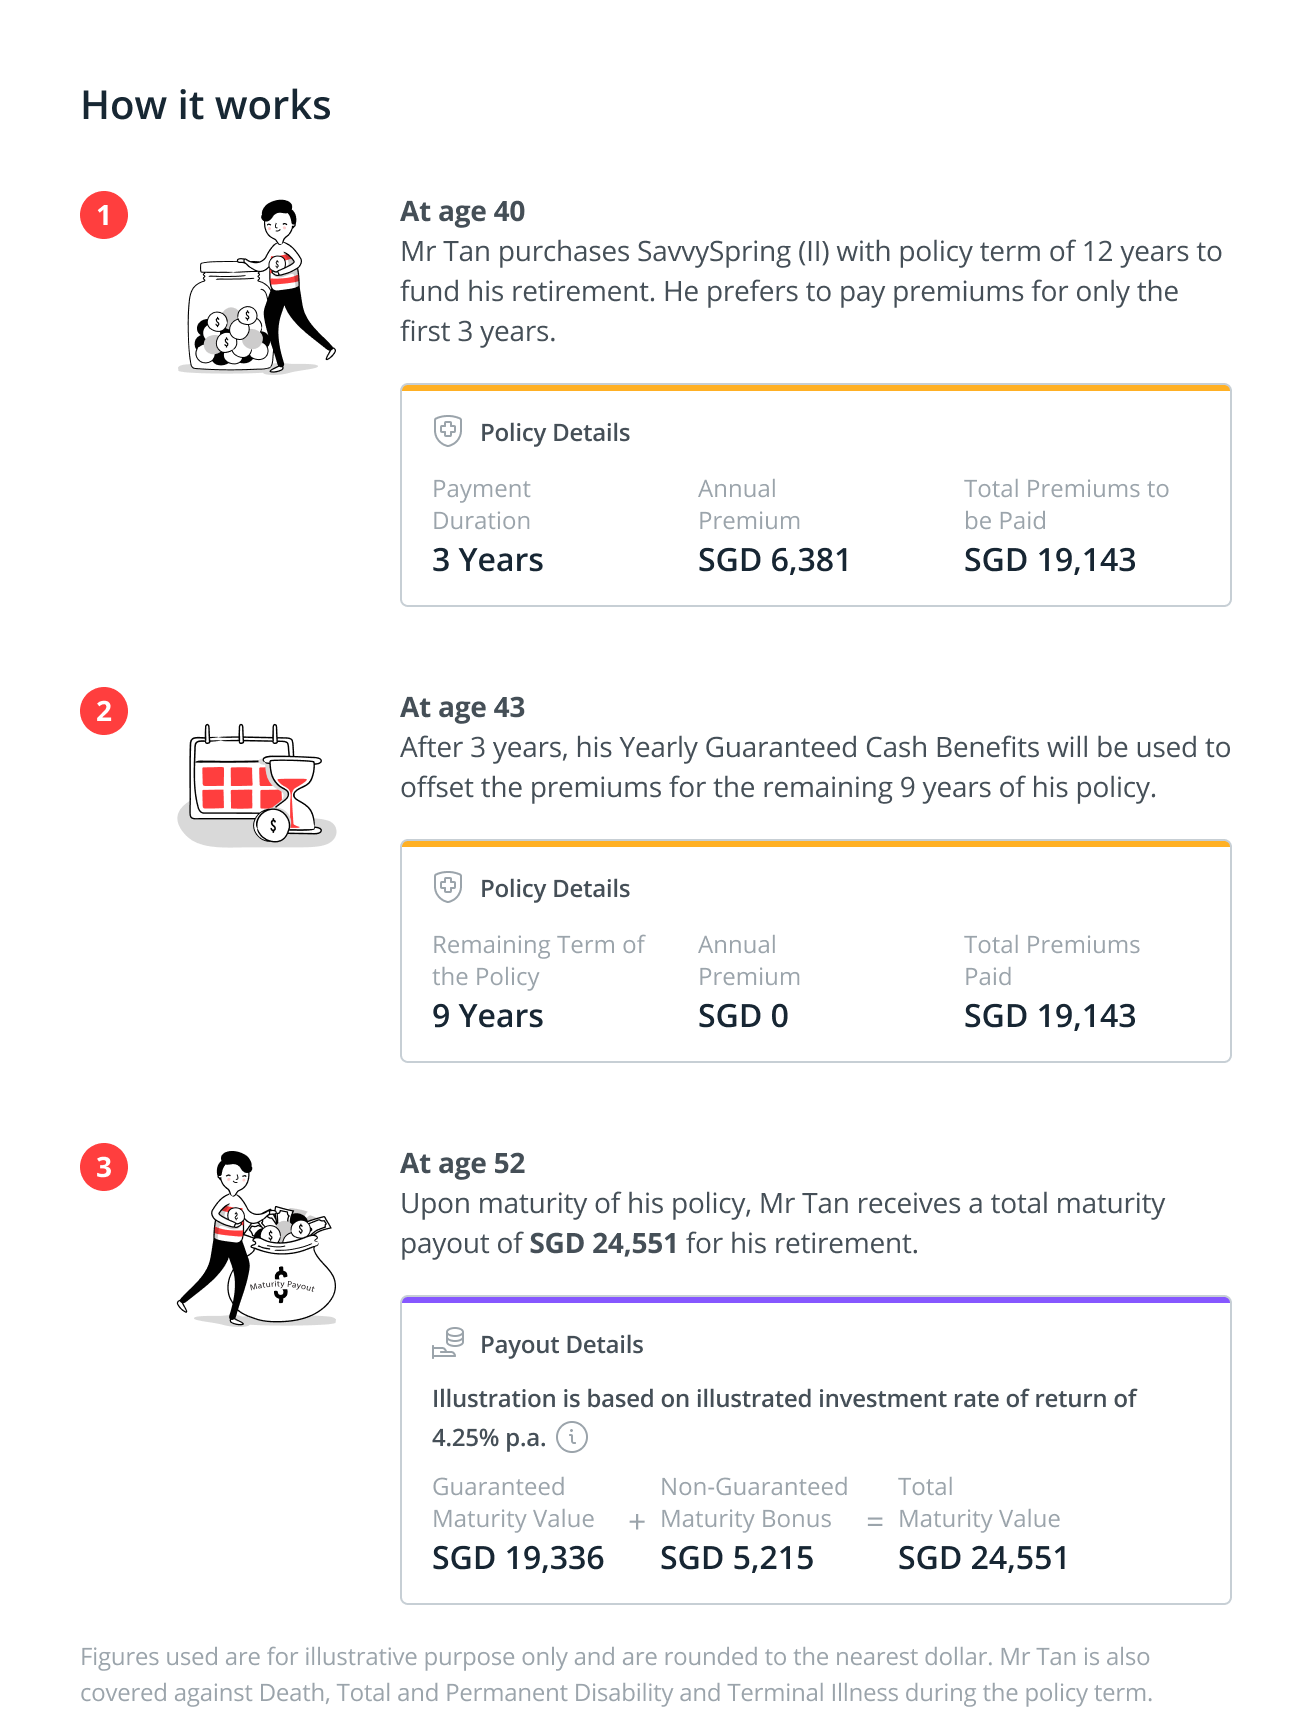
1 Your Yearly Guaranteed Cash Benefit will be used to off-set the annual premium of the basic plan once the Yearly Guaranteed Cash Benefits are payable. Should you prefer to utilize your Yearly Guaranteed Cash Benefits in other ways, you may instruct us accordingly via a written notification after the policy has been issued. You may also choose to receive the Yearly Guaranteed Cash Benefits or accumulate them with Manulife at a non-guaranteed interest rate of 3.00% per annum (at the illustrated investment rate of return of 4.25% per annum) or 1.50% per annum (at the illustrated investment rate of return of 3.00% per annum).
2 Not applicable for policies which have been altered. For paid out and off-set premiums options, capital refers to the total premiums paid by policy owner less off the total Yearly Guaranteed Cash Benefits.
3 Total and Permanent Disability (TPD) benefit covers the life insured until the TPD expiry date. Please refer to product summary for more information on TPD expiry date.
4 Terminal Illness (TI) is any condition caused by illness or injury, where at the time of claim, despite all reasonable medical treatment, the life insured is expected to live for no more than 12 months. In the event of TI during the policy term, the Death Benefit will be advanced in a lump sum.
The medical examiner treating the condition must provide supporting evidence of the condition, possible medical treatment, the prognosis after undergoing the possible medical treatment, and certify that the life insured is expected to live for no more than 12 months despite all possible medical intervention. We reserve the right to appoint an independent medical examiner who is an expert in the condition to confirm the diagnosis and prognosis.
TI in the presence of human immunodeficiency virus (HIV) infection is excluded.
5 Please refer to the policy contract for more information.
Disclaimers
The information herein is published by DBS Bank Ltd (“DBS Bank”) and is for general information only and should not be relied upon as financial advice. This publication may not be reproduced, or communicated to any other person without prior written permission. This website does not take into account the specific investment objectives, financial situation or needs of any particular person. Before entering into any transaction involving any product mentioned in this website, where applicable, you should seek advice from a financial adviser regarding its suitability for your own objectives and circumstances. If you choose not to do so, you should make an independent assessment and do your own due diligence on the product. This advertisement has not been reviewed by the Monetary Authority of Singapore. The website herein is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation.
In Collaboration with Manulife
Manulife Spring (II) & SavvySpring (II) is issued and underwritten by Manulife (Singapore) Pte. Ltd. ("Manulife") (Reg. No. 198002116D) and distributed by DBS. It is not an obligation of, deposit in or guaranteed by DBS.
Buying a life insurance policy is a long-term commitment. An early termination of the policy usually involves high costs and the surrender values payable may be less than the total premiums paid.
This policy is protected under the Policy Owners’ Protection Scheme which is administered by the Singapore Deposit Insurance Corporation (“SDIC”). Coverage for the policy is automatic and no further action is required from you. For more information on the types of benefits that are covered under the scheme as well as the limits of coverage, where applicable, please contact Manulife or visit the Life Insurance Association or SDIC websites (www.lia.org.sg or www.sdic.org.sg).
Deposit Insurance Scheme
Singapore dollar deposits of non-bank depositors and monies and deposits denominated in Singapore dollars under the Supplementary Retirement Scheme are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Monies and deposits denominated in Singapore dollars under the CPF Investment Scheme and CPF Retirement Sum Scheme are aggregated and separately insured up to S$100,000 for each depositor per Scheme member. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured.
Information is correct as at 14 Sep 2025.
DBS Insurance Important Notes
Important Information